What should I do if my roof insurance claim is denied?
Read the denial letter for the reason the carrier gives, then compare it with an independent roof inspection. If the letter says the damage is wear or pre-existing, or the adjuster missed areas, more documentation and a request for reinspection may be appropriate. Check your policy for the deadline and the appeal steps your carrier allows.
The letter names the reason, and the reason sets the next step
A denial letter is required to explain why the claim was not paid. The common reasons on roofs are that the damage is wear and tear rather than storm damage, that it happened before the policy or before the storm date on the claim, that it falls below the deductible, or that the claim was filed after the policy deadline.
Each of those calls for something different. A late-filing denial is hard to reverse. A below-deductible finding is arithmetic worth checking. A wear-and-tear finding is where documentation matters most, because it is a judgement about what the adjuster saw on the roof.
Wind and hail damage are easy to call wear
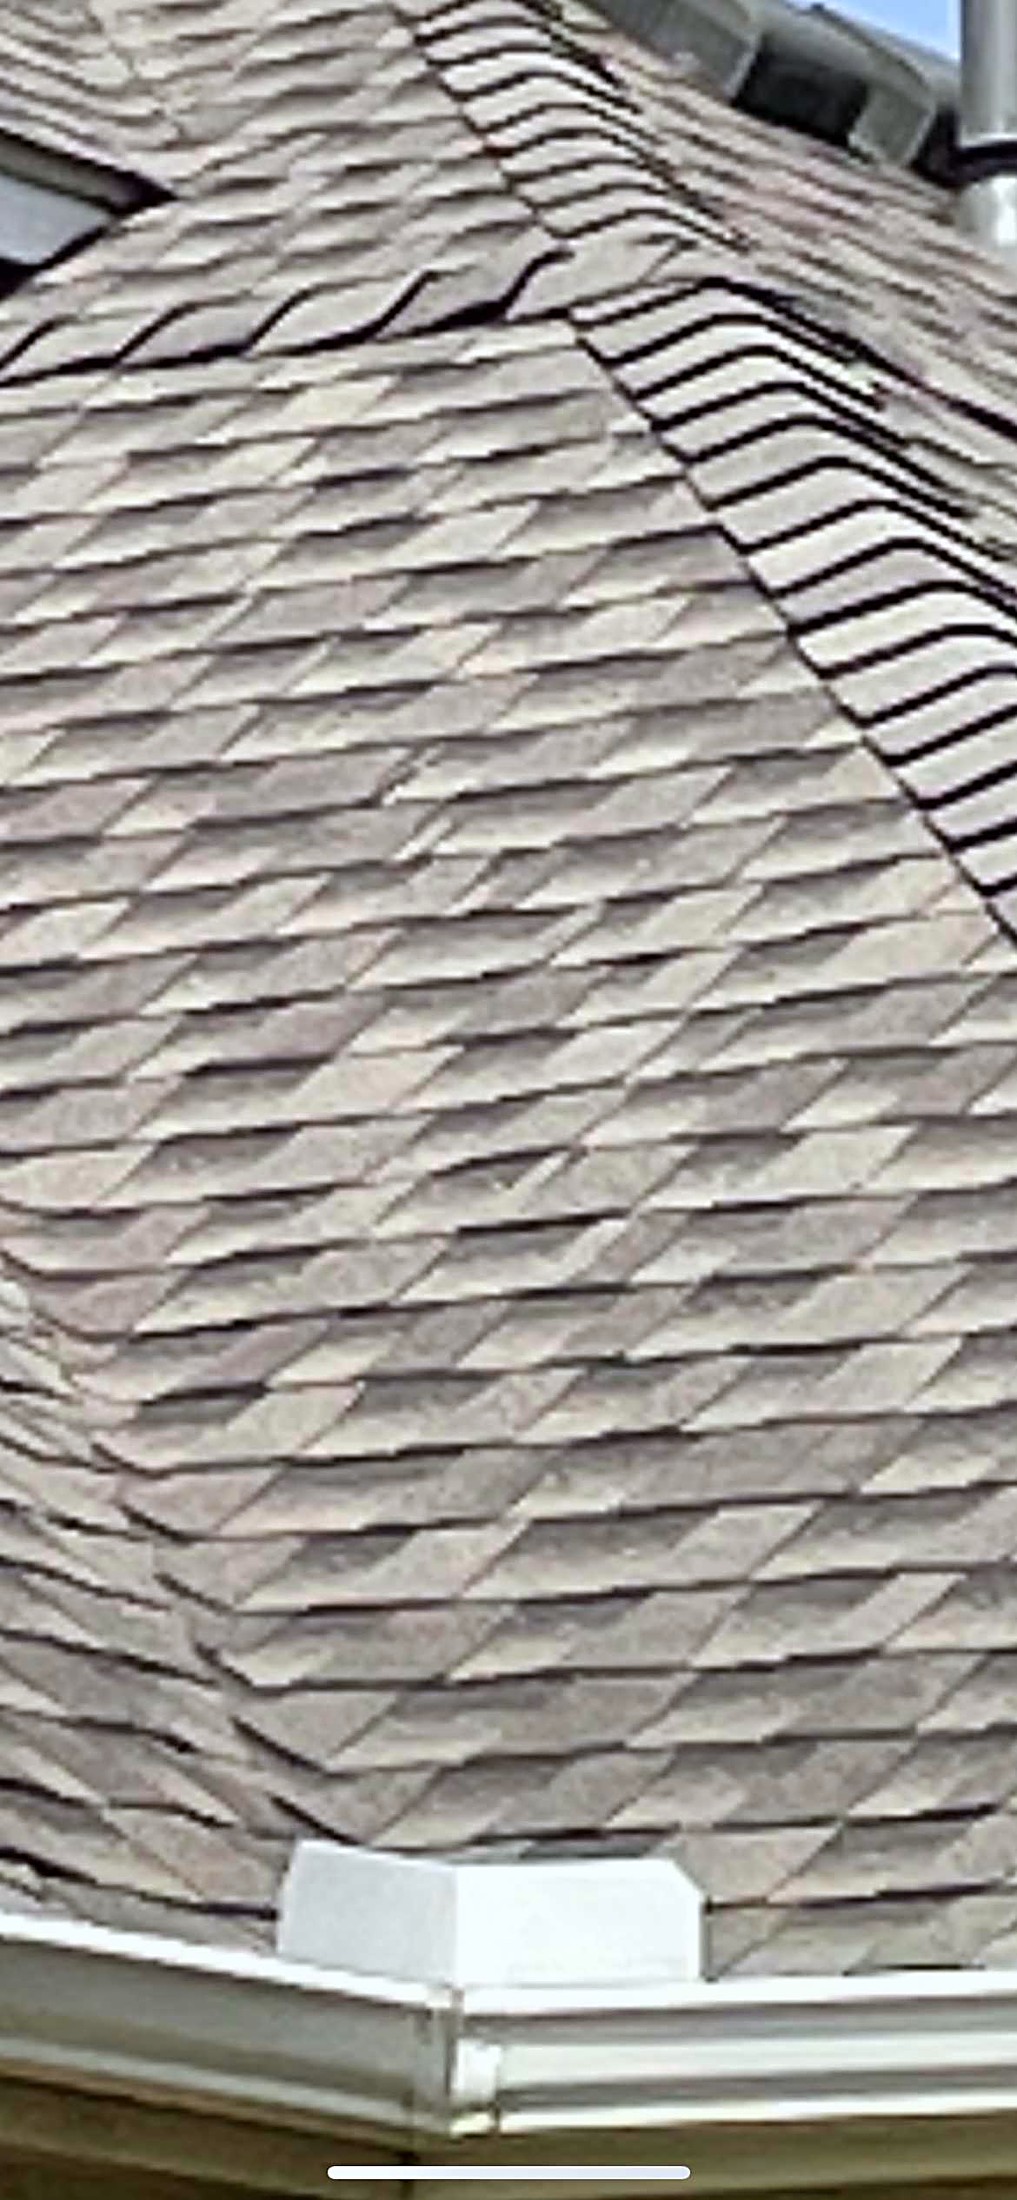
Hail bruises and granule loss can look like ordinary aging to someone moving quickly across a roof, and wind damage is harder still, because a lifted shingle often lies back down after the storm with its seal strip broken underneath. Damage to gutters, vents, screens and AC fins from the same storm is often the clearest evidence that the roof took hits too.
An independent inspection with dated photos of the roof and the exterior gives you something specific to set beside the adjuster’s report.
Asking for another look
Many carriers allow a reinspection or an internal review when new documentation is provided. Ask your carrier in writing what review process applies to your claim and by when. Keep copies of everything you send and receive.
Texas policies may also include an appraisal clause for disputes over the amount of a loss, and the Texas Department of Insurance takes consumer complaints. Your policy and your agent are the places to confirm which options apply to you.
What a contractor can and cannot do
A roofer can inspect the roof, document the damage, review the denial with you and explain what it means. A roofer cannot adjust the claim, negotiate coverage on your behalf or promise an outcome, and a contractor who offers to do any of those deserves more questions.
Related questions
Can a denied roof claim be reopened?
Often a carrier will review new documentation or allow a reinspection. Ask your carrier in writing what applies to your claim.
Should I get my own roof inspection after a denial?
Yes. An independent inspection with dated photos gives you something concrete to compare with the adjuster’s findings.